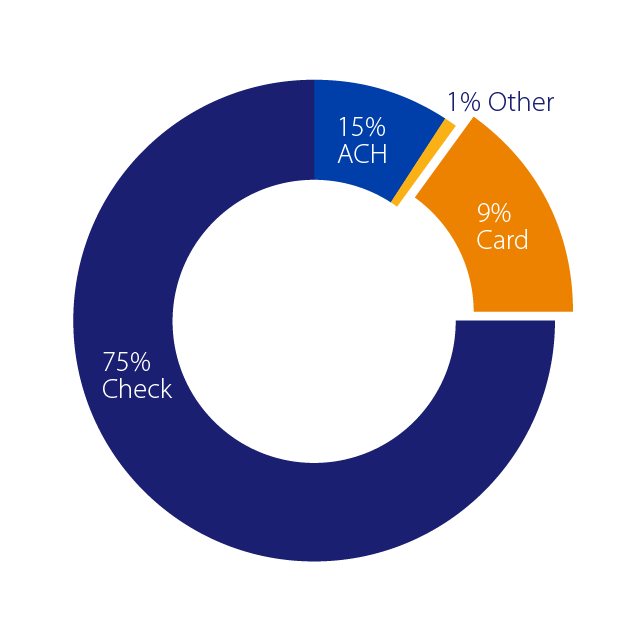
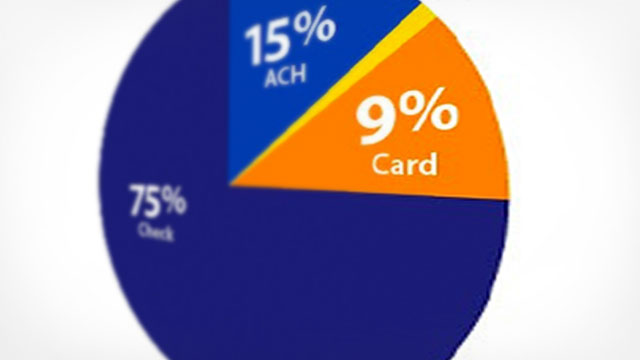
Small business credit card spending represents a $5.8 trillion opportunity for issuers1. While business card spending has been growing at 10+ percent per year, and at even more than 20 percent in the second half of 20162, it only accounts for 9 percent of overall spending compared to other payment methods. 1This is because small business owners face unique challenges that many issuers haven’t yet solved and issuers are not offering card products that meet their needs.
Small Business Credit Optimization
Small business payment methods1
Small business challenges2
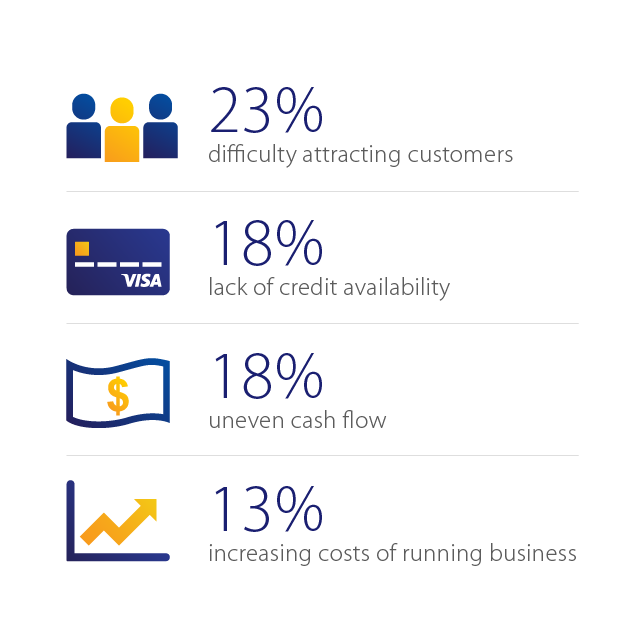
To capture more of this spend, issuers need to address these pain points, such as the lack of credit availability, uneven cash flow and the increasing costs of running a small business.
The average small business owner spends about $22,000 per month in business expenses. An average high-revenue business spends over $70,000 per month. There are ~29 million small businesses in the U.S. that can be supported by solving their major pain points2.
Pain points to address to drive stickiness and payment volume
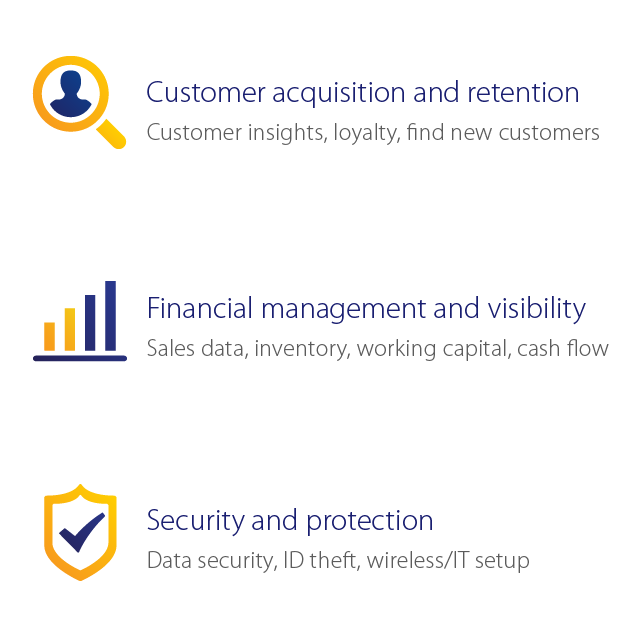
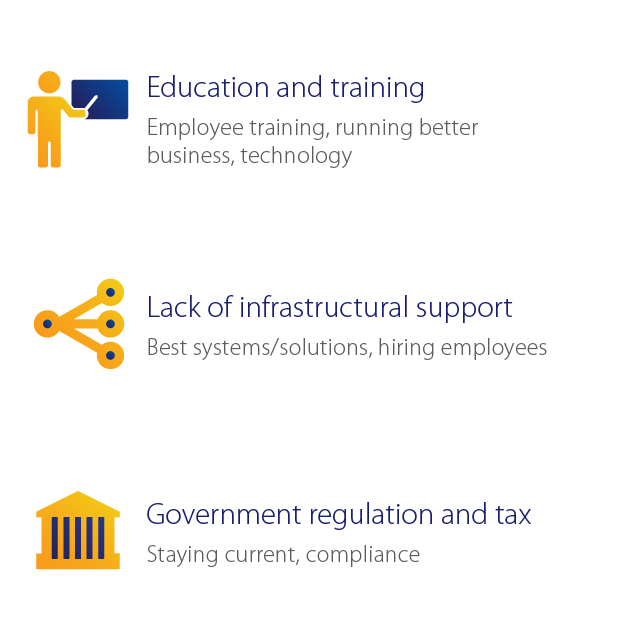
Small business owners are a unique customer segment with specific expectations. They require a customized approach and products that address their needs.
We can help you capture this opportunity and ensure that you have the right strategy to serve small business customers.
Two reasons you may need small business credit optimization
- You don’t have a small business credit product and you’re interested in entering the market.
- Use small business credit optimization to assess the market, identify and size the opportunity, and develop a market entry strategy that is unique to you.
- You have a small business credit product and you would like to optimize its performance.
- Use small business credit optimization to analyze your current portfolio, identify and size the opportunity for growth, and develop an implementation strategy designed for you.
Whether your financial institution already has a mature credit product in the market or you’re thinking of launching a new credit product, Visa’s custom-designed solutions will give you concrete, actionable steps to take. We will provide support through implementation to ensure that you can deliver the right small business credit product to the right customers.
We can also provide you with comprehensive insights and analytics to inform your approach. We can help you with:
- Market and issuer assessment: We’ll provide a detailed view of the full industry landscape, including data that reflects how peers are performing, what customers are looking for, and how your products (if any) compare to the market.
- Segmentation strategy and analytics: We’ll use Visa’s proprietary data to recommend segmentation and targeting schemes, which lead to the highest return on investment (ROI).
- Go to market/launch roadmap: We’ll offer comprehensive recommendations for launch, including implementation considerations and proven best practices.
Our approach
We estimate three phases spanning six to 12 weeks for project completion. Following are typical project phases:
Phase One
- Review small business market industry trends and competitors’ performance to size opportunity specifically for you
- Examine your current portfolio and strategy (if applicable)
- Assess customer needs
Phase Two
- Synthesize insights
- Identify gaps in current portfolio versus peers and customer needs
- Develop new or optimize existing products based on the uncovered opportunities
Phase Three
- Provide implementation recommendations on product and marketing strategies
- Develop full end-to-end roadmap for going to market
Contact us for more information about this service.
Sources
1 Visa Commercial Consumption Expenditure Index; Economist Intelligence Unit (EIU) modeling and analysis, December 2015. Global CCE index data sources include Bureau of Economic Analysis (BEA), U.S. Census Bureau, Organization for Economic Cooperation and Development (OECD), Structural ANalysis (STAN) Database, EuroStat Database, General Government Accounts from the National Accounts of OECD Countries, United Nations Statistics Division National Accounts Main Aggregates Database, EIU proprietary databases, government data and EIU model estimates where government data was unavailable. Large contracted defense spending not included in CCE index.
2 Expanding Small Business Card Programs, Phoenix Synergistics, November 2016.
3 Visa Small Business Payments Behavior Study 2016, Waves 3 & 4.
4 VisaNet Q2 2014 – Q4 2016 data.
You may also be interested in
Small business credit and debit marketing
Capture more spend for your small business program.
Six ways to attract millennials as bank customers
Initiate lifelong banking relationships.
Portfolio Performance Assessment quizzes
See how your business practices measure up against global best practices.